

Asian Petrochemical Market Scan
Asian Petrochemical Market Scan: Broad-Based Price Recovery in the Final Week of October 2026
Global Petrochemical Price Analysis | October 23–30, 2026
The Asian petrochemical market experienced a notable shift in pricing trends during the final week of October 2026. Following a period of declining prices across several major petrochemical products, the market showed signs of recovery, with most of the products covered in this report recording weekly price increases.
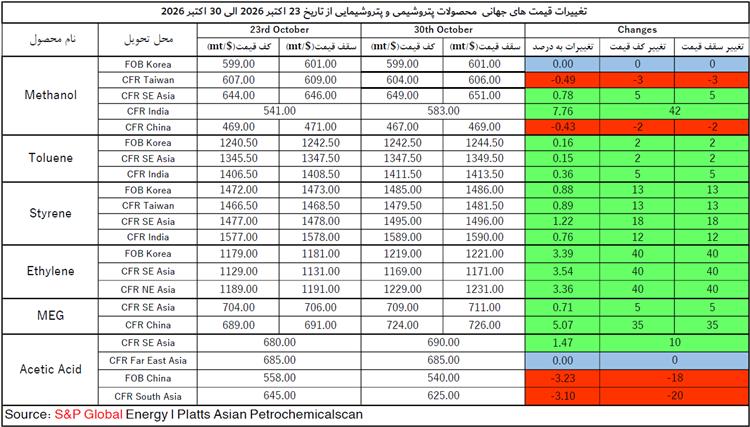
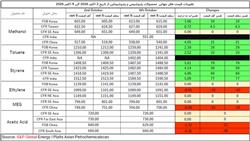
According to S&P Global Energy | Platts data, out of 21 regional price assessments covering six major petrochemical products, 15 recorded increases, four declined, and two remained unchanged.
Ethylene led the market in terms of absolute price gains, increasing by $40/MT across all three assessed markets. Methanol recorded a significant 7.76% increase in India, while MEG prices rose by 5.07% in China. Styrene and toluene also posted gains across their respective Asian markets.
However, acetic acid continued to face downward pressure in China and South Asia, highlighting the different supply-demand dynamics across petrochemical value chains.
1. Methanol: Strong Recovery in India Amid Mixed Regional Performance
Methanol prices showed mixed movements across Asian markets during the week ending October 30. While India and Southeast Asia recorded price increases, Taiwan and China experienced slight declines.
Weekly price changes:
FOB Korea: Unchanged at $599–601/MT.
CFR Taiwan: Decreased by $3/MT, or 0.49%.
CFR Southeast Asia: Increased by $5/MT, or 0.78%.
CFR India: Increased by $42/MT, or 7.76%.
CFR China: Decreased by $2/MT, or 0.43%.
The most significant development was the sharp increase in India's methanol market, where prices rose from $541/MT to $583/MT, representing a weekly gain of $42/MT.
This increase was considerably higher than movements in other regional markets and may reflect changes in import demand, cargo availability, or purchasing activity among Indian consumers.
In contrast, China's methanol market remained relatively weak, with prices declining slightly to $467–469/MT.
Nevertheless, the magnitude of the decline in China was considerably smaller than in the previous reporting period, suggesting a potential stabilization in the market.
2. Toluene: Continued Price Growth Across Asian Markets
Toluene maintained its upward trend during the final week of October, with all three assessed markets recording price increases.
Weekly price changes:
FOB Korea: Increased by $2/MT, or 0.16%.
CFR Southeast Asia: Increased by $2/MT, or 0.15%.
CFR India: Increased by $5/MT, or 0.36%.
The highest increase was recorded in India, where prices reached $1,411.50–1,413.50/MT.
Although the increases were relatively modest, the consistent upward movement across all three markets indicates continued price support.
Key factors influencing toluene prices include crude oil and naphtha movements, aromatic market conditions, gasoline blending demand, and industrial solvent consumption.
3. Styrene: Broad-Based Recovery Across Regional Markets
Styrene recorded price increases across all four assessed Asian markets, reversing the downward trend observed during the previous reporting period.
Weekly price changes:
FOB Korea: Increased by $13/MT, or 0.88%.
CFR Taiwan: Increased by $13/MT, or 0.89%.
CFR Southeast Asia: Increased by $18/MT, or 1.22%.
CFR India: Increased by $12/MT, or 0.76%.
Southeast Asia recorded the strongest increase, with styrene prices rising from $1,477–1,478/MT to $1,495–1,496/MT.
Styrene is a key feedstock for polystyrene, ABS, and several other polymer products. Therefore, price movements in this market are closely connected to downstream manufacturing activity.
The simultaneous price increases across all assessed markets may indicate improved market sentiment, tighter supply conditions, or stronger purchasing interest.
Future price movements will depend heavily on benzene and ethylene prices, styrene production rates, and demand from downstream polymer manufacturers.
4. Ethylene: Leading Price Increases in the Asian Petrochemical Market
Ethylene remained one of the strongest-performing products during the final week of October.
All three assessed markets recorded an identical absolute increase of $40/MT.
Weekly price changes:
FOB Korea: Increased from $1,180 to $1,220/MT, up 3.39%.
CFR Southeast Asia: Increased from $1,130 to $1,170/MT, up 3.54%.
CFR Northeast Asia: Increased from $1,190 to $1,230/MT, up 3.36%.
The synchronized $40/MT increase across all three markets is particularly significant, indicating that the upward movement was not limited to an individual regional market.
Ethylene is a fundamental petrochemical feedstock used in the production of polyethylene, ethylene oxide, and various other chemical derivatives.
Consequently, sustained ethylene price increases may translate into higher production costs for downstream manufacturers, particularly polyethylene producers.
The continued upward movement in ethylene prices over consecutive reporting periods makes this product one of the most important bullish indicators in the current Asian petrochemical market.
5. Monoethylene Glycol (MEG): Strong Price Recovery in China
Monoethylene glycol (MEG) prices increased in both assessed markets, although the magnitude of the increase differed significantly between China and Southeast Asia.
Weekly price changes:
CFR Southeast Asia: Increased by $5/MT, or 0.71%.
CFR China: Increased by $35/MT, or 5.07%.
Chinese MEG prices increased from $689–691/MT to $724–726/MT.
This recovery is particularly noteworthy considering that the Chinese market experienced only a relatively modest decline during the previous reporting period.
The 5.07% weekly increase suggests a significant improvement in pricing conditions compared with the previous week.
In contrast, Southeast Asian prices increased by only $5/MT, indicating a more moderate recovery in that market.
MEG is a critical raw material in the production of PET, polyester fibers, and unsaturated polyester resins. Therefore, price increases may affect production costs across the textile, packaging, polyester, and resin industries.
Key indicators to monitor include purified terephthalic acid (PTA) prices, paraxylene market conditions, PET production rates, and inventory levels in China.
6. Acetic Acid: Continued Downward Pressure in China and South Asia
Unlike most other products covered in this report, acetic acid continued to experience mixed but predominantly bearish market conditions.
Weekly price changes:
CFR Southeast Asia: Increased by $10/MT, or 1.47%.
CFR Far East Asia: Unchanged at $685/MT.
FOB China: Decreased by $18/MT, or 3.23%.
CFR South Asia: Decreased by $20/MT, or 3.10%.
The largest absolute decline occurred in South Asia, where prices fell from $645/MT to $625/MT.
FOB China prices also declined significantly, reaching $540/MT.
However, Southeast Asia moved in the opposite direction, with prices increasing by $10/MT to $690/MT.
These contrasting movements highlight regional differences in supply-demand conditions and trading activity.
Acetic acid is an important feedstock for vinyl acetate monomer (VAM), acetate derivatives, industrial solvents, and various chemical intermediates.
Continued price weakness in China and South Asia suggests that product-specific supply and demand factors are still exerting downward pressure, despite the broader recovery in the Asian petrochemical market.
7. Comparative Analysis: Biggest Weekly Price Movements
A comparison of the major price movements provides a clearer picture of market performance.
Largest price increases:
| Product / Market | Price Change | Percentage |
|---|---|---|
| Methanol CFR India | +$42/MT | +7.76% |
| Ethylene FOB Korea | +$40/MT | +3.39% |
| Ethylene CFR Southeast Asia | +$40/MT | +3.54% |
| Ethylene CFR Northeast Asia | +$40/MT | +3.36% |
| MEG CFR China | +$35/MT | +5.07% |
Largest price decreases:
| Product / Market | Price Change | Percentage |
|---|---|---|
| Acetic Acid CFR South Asia | -$20/MT | -3.10% |
| Acetic Acid FOB China | -$18/MT | -3.23% |
| Methanol CFR Taiwan | -$3/MT | -0.49% |
| Methanol CFR China | -$2/MT | -0.43% |
Ethylene stands out for the consistency and geographical breadth of its price increases. Meanwhile, methanol in India and MEG in China recorded the strongest percentage gains.
Acetic acid remained the main exception to the broader recovery.
8. Comparison with the Previous Reporting Period: Is the Market Entering a Bullish Phase?
Comparing the October 9–23 and October 23–30 reporting periods reveals a meaningful change in market direction.
During the earlier period, methanol, styrene, MEG, and acetic acid experienced widespread price declines. However, the latest data show a recovery in most of these products.
Key developments include:
Ethylene: Continued its upward movement, recording another $40/MT increase across all assessed markets.
Styrene: Reversed its previous downward trend and increased across all four regional markets.
MEG: Recovered in both China and Southeast Asia, with particularly strong growth in China.
Methanol: Recorded a substantial increase in India, although China and Taiwan remained slightly weaker.
Acetic Acid: Continued to face downward pressure in China and South Asia.
These developments suggest that the Asian petrochemical market is moving away from the broad-based weakness observed earlier in October.
However, one week of widespread price increases is not sufficient to confirm the beginning of a sustained bullish cycle. Further monitoring of demand, supply availability, inventories, and feedstock costs will be necessary.
9. Market Outlook: Key Factors to Watch
Several fundamental factors will influence petrochemical prices in the coming weeks.
Crude Oil and Naphtha Prices
Changes in crude oil and naphtha prices directly influence production economics across several petrochemical value chains, particularly ethylene and aromatic products.
Chinese Demand and Inventory Levels
China remains a major driver of Asian petrochemical prices. Import activity, inventory levels, and downstream operating rates will be essential indicators of future market direction.
Production Capacity and Operating Rates
Maintenance shutdowns, unexpected production interruptions, new capacity additions, and changes in plant operating rates can significantly alter regional supply-demand balances.
Downstream Industry Performance
Demand from polyethylene, PET, polystyrene, ABS, polyester fiber, and industrial resin manufacturers will remain a critical factor in determining the sustainability of the current price recovery.
Freight and International Trade Conditions
Shipping costs, logistics constraints, exchange rates, and international trade conditions can influence delivered prices and regional competitiveness.
Conclusion
The Asian petrochemical market demonstrated a broad-based price recovery during the week ending October 30, 2026.
Ethylene led the upward movement, with a $40/MT increase across all three assessed markets. MEG prices recovered significantly in China, while styrene and toluene also recorded gains across their respective regional markets.
Methanol showed a particularly strong recovery in India, although prices in China and Taiwan remained slightly lower.
Acetic acid continued to diverge from the broader market trend, with significant declines in China and South Asia.
For petrochemical traders, manufacturers, and raw material buyers, these developments are important for procurement planning, inventory management, and evaluating short-term market opportunities.
Key Takeaway: The Asian petrochemical market showed clear signs of a price recovery in the final week of October 2026. Nevertheless, diverging regional trends and product-specific fundamentals indicate that purchasing and trading decisions should be based on individual product analysis rather than the overall market direction.
Data Source: S&P Global Energy | Platts – Asian Petrochemicalscan
Reporting Period: October 23–30, 2026
Price Unit: US Dollars per Metric Ton (USD/MT)

Comments (0)
Post a comment